What is the Starter Health Monitor Market scope and industry significance?
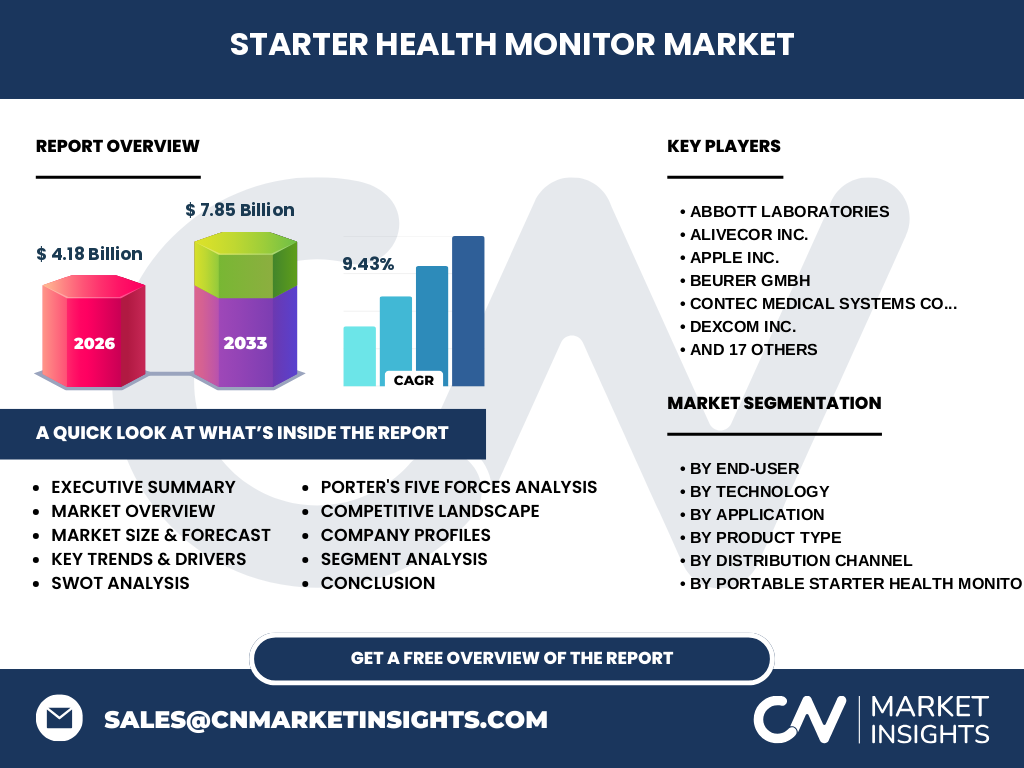
Our analysis indicates that the Starter Health Monitor Market is valued at 4.18 Billion in 2026. This sector encompasses entry-level diagnostic tools, empowering decentralized patient care across hospitals, fitness facilities, and households by streamlining early symptom detection.
Key market drivers, restraints, challenges, and opportunities shaping Starter Health Monitor Market
Growth is propelled by rising chronic disease burdens and digital literacy. However, regulatory hurdles imposed by the FDA and data privacy mandates restrict rapid cross-border deployment, presenting notable supply chain bottlenecks for imported silicon sensors.
Emerging trends and growth patterns in Starter Health Monitor Market
The market is witnessing a rapid pivot toward Cloud-Connected Monitoring and Bluetooth-enabled ecosystems. Patients increasingly demand seamless telemetry integration, shifting industry focus from standalone hardware to subscription-backed digital wellness portfolios.
COVID-19 impact analysis — how the pandemic affected Starter Health Monitor Market and the recovery trajectory
The pandemic drastically accelerated remote triage adoption. Supply chains faced acute shortages of specialized microcontrollers sourced from Asian manufacturing hubs, yet post-pandemic recovery has surged as healthcare providers institutionalize decentralized monitoring protocols.
Competitive benchmarking and strategic dynamics
Market concentration remains moderately fragmented, featuring tech giants and medical device veterans. Industry leaders leverage proprietary cloud infrastructure to lock consumers into closed-loop ecosystems, outpacing traditional hardware suppliers.
Executive summary of the Starter Health Monitor Market
Driven by a robust 9.43% CAGR, the market will expand from 4.18 Billion in 2026 to 7.85 Billion by 2033. Strategic investments in sensor miniaturization and AI-driven predictive analytics represent the primary value capture zones.
Starter Health Monitor Market forecast from 2027 to 2033
Our research forecasts exponential revenue scaling, surging from baseline 2027 estimates to reach 7.85 Billion by 2033. This trajectory is underpinned by surging adoption rates among aging demographics requiring continuous physiological tracking.
Segmentation analysis across end-users, technologies, applications, and product types
Segmentation spans end-users (Adults, Children, Elderly), technologies (Bluetooth, Wi-Fi, Cellular, Sensor-Based, Cloud-Connected), applications (Homecare, Hospitals, Fitness Centers), and product types (Wearable, Portable, Stationary), tailoring solutions to distinct clinical and lifestyle demands.
Regional market analysis and geographic distribution performance
North America dominates revenue share due to established digital infrastructure, while Asia-Pacific exhibits the fastest adoption velocity, driven by expanding middle-class demographics and localized manufacturing clusters in South Korea and China.
In-depth regional review of key markets
North American markets prioritize reimbursement-backed clinical devices, whereas European markets emphasize strict CE-mark compliance for wellness wearables. Emerging APAC sectors lean heavily on mobile-first, app-integrated portable diagnostic tools.
Company profiles and strategic positioning of leading players
Industry titans like Apple Inc., Abbott Laboratories, and Medtronic plc dominate through aggressive R&D. Meanwhile, specialized innovators like AliveCor Inc. and DexCom Inc. carve niches via targeted diagnostic accuracy.
Porter's Five Forces analysis of competitive intensity
Threat of new entrants remains moderate due to stringent medical device compliance, while supplier power over specialized semiconductor components keeps profit margins tight for mid-tier hardware assemblers.
SWOT analysis of the Starter Health Monitor industry
Strengths lie in high consumer health consciousness and advanced sensor tech. Weaknesses involve data privacy vulnerabilities. Opportunities emerge in remote eldercare, while threats stem from aggressive regulatory crackdowns on consumer health software.
Value chain analysis from raw materials to end-users
The value stream begins with raw semiconductor sourcing and biochemical reagent fabrication, flowing through OEM assembly plants, and terminating via online retail, pharmacies, and specialty healthcare distributors.
Investment insights and strategic recommendations
Investors should target early-stage developers specializing in interoperable cloud-connected monitoring software. Companies possessing robust cybersecurity frameworks will capture outsized valuation multiples as healthcare compliance tightens globally.
Conclusion and key takeaways for stakeholders
The market presents exceptional growth velocity heading toward 2033. Success hinges on navigating complex regulatory pathways while delivering frictionless, highly accurate consumer-grade health diagnostics.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary stakeholder interviews with C-level medical executives, and secondary macroeconomic indicators from global health organizations.
Scope of the report and coverage parameters
This report evaluates global market dynamics, revenue forecasts, and competitive positioning across specified segments from 2026 through 2033, excluding bespoke veterinary diagnostic hardware and unverified direct-to-consumer wellness gadgets.
Recent developments, product launches, and strategic partnerships
Recent market dynamism includes strategic acquisitions and FDA clearances for advanced wearable glucose and ECG sensors by key participants, signaling an aggressive push into predictive preventative medicine.